Understanding the PPP model
A PPP generally involves a private partner designing, financing, constructing, operating and maintaining an infrastructure asset or public service for an agreed concession period. Depending on the project, the private partner may recover its investment through user charges, availability payments from the public authority, payments linked to service volumes or performance, offtake agreements, commercial revenues associated with the asset, or a combination of public and private sources.
Common contractual models include Design–Build–Finance–Operate–Maintain, Build–Operate–Transfer, Build–Own–Operate–Transfer, concession agreements, lease-and-operate structures, energy-performance contracts, and joint ventures between public and private entities. The appropriate model depends on the asset, the revenue profile, public-service obligations, the legal framework and risk allocation.
Why it matters across the six economies
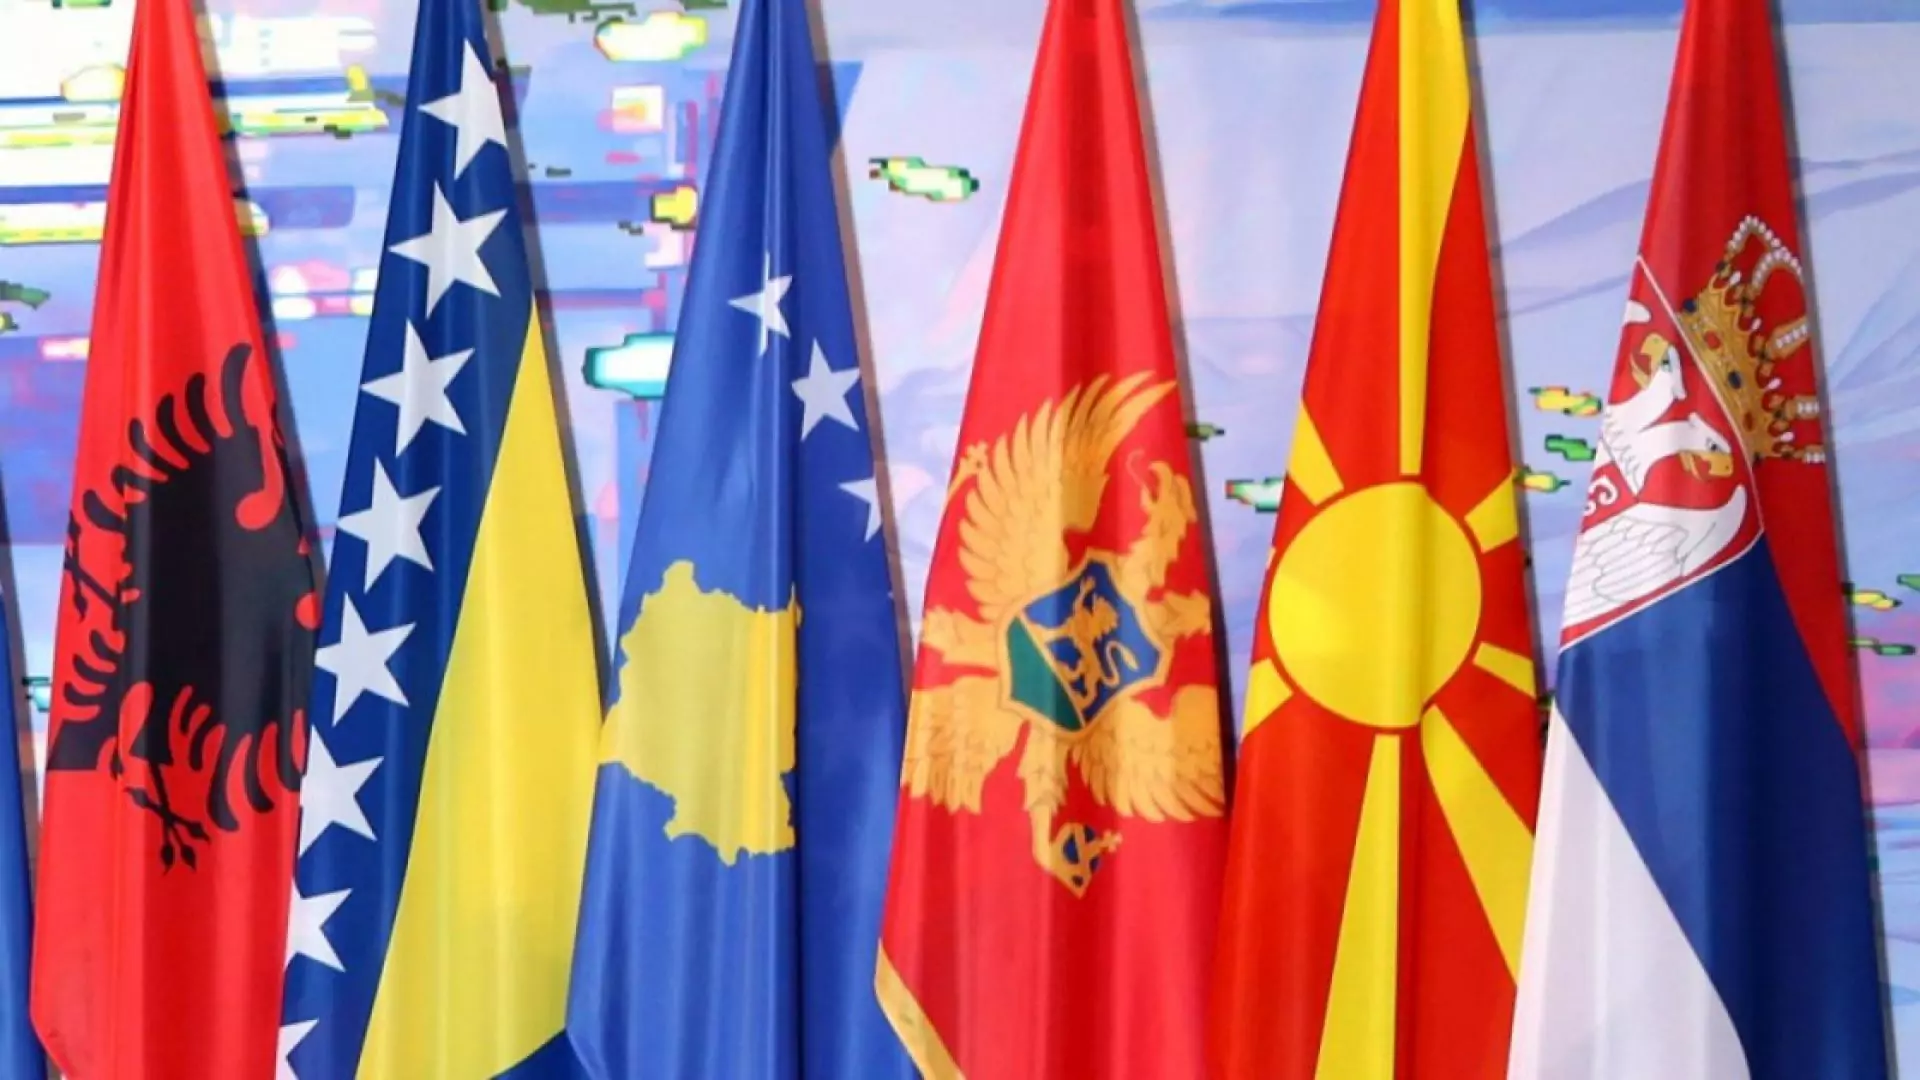
Across Albania, Bosnia and Herzegovina, Kosovo, Montenegro, North Macedonia and Serbia, infrastructure development remains fundamental to economic convergence with the European Union. Properly structured PPPs can accelerate delivery, transfer selected construction and operational risks, introduce lifecycle maintenance obligations, and mobilise financing not otherwise available through public budgets.
They also create a single point of accountability: the private partner is responsible not only for constructing the asset, but for ensuring it performs over an extended period.
- Roads, railways, airports and urban transport
- Renewable energy, storage and electricity networks
- District heating and energy efficiency
- Water supply, wastewater treatment and climate resilience
- Solid-waste and circular-economy infrastructure
- Hospitals, schools, student accommodation and public buildings
- Broadband, data and digital infrastructure
- Logistics, industrial parks and border facilities
How the financing is structured
A bankable PPP is normally financed through a special-purpose vehicle established by the selected private consortium. The project company enters into the PPP agreement with the public authority and appoints construction, operation and maintenance contractors under separate project agreements. Lenders rely primarily on the project’s contracted cash flows rather than on the sponsors’ general balance sheet, which is what makes the quality of the contract, the revenue mechanism and the risk allocation fundamental to financing.
The capital stack runs, in order of seniority: senior debt from commercial banks, international financial institutions and development banks; subordinated or mezzanine capital; and sponsor equity from developers, operators, construction companies, infrastructure funds and strategic investors, which takes first loss. Public contributions, blended and concessional finance, and climate-linked funding can sit alongside the stack as viability support. Proportions vary by project and none is implied here.
Revenue models, and who carries demand risk
Projects generally fall into three categories. Under user-pay, revenue comes directly from users — airports, toll roads, parking, certain utilities — and demand risk sits largely with the private partner, which requires credible usage forecasts, a workable tariff framework and protection against discriminatory regulatory change. Under government-pay, availability payments begin once the asset is operational and meets performance standards; demand risk is retained by the authority, which improves revenue predictability but creates long-term fiscal commitments. Hybrid structures combine user revenue with public payments, grants or minimum-revenue mechanisms, for projects that are economically justified but cannot recover full cost at affordable tariffs.
Public support should be transparent, limited to what is necessary, and incorporated into the project’s value-for-money and fiscal-affordability assessments.
What makes a PPP bankable
Private capital will not finance a project solely because it is strategically important. A PPP must convert public need into a predictable and enforceable investment proposition.
- A clearly defined public need and service standard
- A technically feasible and appropriately scoped project
- Credible capital-cost and operating-cost estimates
- Transparent and competitive procurement
- An enforceable long-term contract
- A reliable revenue or payment mechanism, with appropriate tariff adjustment and indexation
- Realistic demand projections
- Secure land rights and permits
- Defined environmental and social obligations
- Protection against political and discriminatory regulatory risk
- Effective dispute resolution and lender step-in rights
- A balanced termination-compensation regime
- An affordable government-payment profile
- Capable public and private counterparties
Risk transfer has a limit
Risk should be transferred only where the receiving party can manage it efficiently. Excessive transfer of political, demand, land, permitting or force-majeure risk does not protect the public authority — it makes the project unfinanceable, or substantially increases its cost. This is the single most common structural error we see in regional projects.
The role of international financial institutions
International financial institutions matter disproportionately in regional PPPs. They support projects through early-stage technical assistance, legal and financial advisory, feasibility and environmental studies, long-term senior debt, syndicated and parallel financing, political-risk mitigation, guarantees and risk-sharing instruments, climate and sustainability-linked finance, procurement and governance requirements, and the mobilisation of commercial lenders and institutional investors.
The EBRD has pointed to Serbia’s Belgrade Airport concession and the Vinča waste-to-energy project as regional examples of complex infrastructure PPPs supported by international finance and structured around long-term private participation, emphasising balanced risk allocation, transparent procurement, institutional capacity and credible project preparation as success factors.
The EIB Group reported investing €822 million across the Western Balkans in 2025, illustrating the continuing role of development-finance institutions in the region’s infrastructure, energy-transition and private-sector agenda. That figure represents wider EIB Group activity and should not be read as PPP financing alone.